
The Board's Role in M&A Has Changed, and Most Boards Haven't

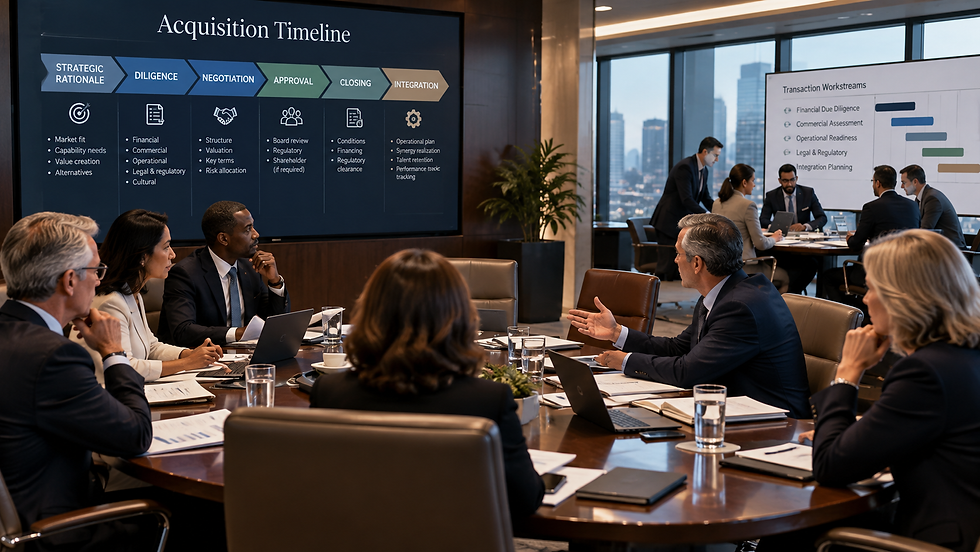
Many boards are built around a calendar. Quarterly meetings, committee cycles, an annual strategy session. That structure suits oversight. It suits a live transaction far less, because a deal runs on a clock someone else sets.
The strain runs both ways. Management needs answers in days. Directors need enough information to give those answers honestly. The board's role in M&A sits at that pressure point, and I'd argue a board that designs its M&A governance during a live transaction is already behind the deal. No source I found counts how many boards have rebuilt their approach, so that view is my judgment.
What has changed is how much of a deal a board is expected to touch, and how little of it fits inside a scheduled meeting.
The Deal Clock Belongs to Someone Else
Boards rarely choose when a transaction starts, and they rarely control how long it runs. A counterparty applies pressure. A regulator sets a review period. In some jurisdictions, a rulebook sets the timetable itself.
The United Kingdom offers a clear example. According to the law firm Slaughter and May, in A Guide to Takeovers in the United Kingdom, a publicly identified potential bidder has 28 days to announce a firm offer or announce that it won't make one, unless the Takeover Panel agrees to extend the deadline. Once a target board is approached, the Takeover Code also bars it from actions that could frustrate an offer unless shareholders approve or the Takeover Panel consents. The Code applies mainly to UK-listed targets, so many boards will never meet it. The lesson travels anyway. Without a rulebook, a bidder, a seller, or a lender can still impose a deadline, and directors still have to be informed when they vote.
Speed also arrives from inside the company. Partners at the law firm Cravath, Swaine & Moore LLP wrote in M&A, Activism and Corporate Governance, posted to The Harvard Law School Forum on Corporate Governance, that on public deals above $10 billion, the higher stakes of a leak mean everyone involved must be ready to move twice as quickly from decision to signing and announcement. That memo addresses deal professionals and very large public deals, so it doesn't describe every board. Mitchell Sabshon, lead independent director of Seritage Growth Properties, describes the internal version in The Board's Role in Merger and Acquisition Oversight, published in Directors & Boards. He names a pattern he calls deal mania, in which management urges speed and the board has to hold off until diligence is done. The law firm Goodwin, citing analysis by the consulting firm Boston Consulting Group, reports in M&A Deal Timelines Rise Across the Globe that signing to closing takes 27% longer above $10 billion than at $2 billion to $10 billion.
Board materials set a pace too. The National Association of Corporate Directors (NACD) and Board Intelligence, a board-software provider, report in Board Packs: The Elephant in the Boardroom that directors prefer the board pack 7 days before a meeting. Maureen Bujno of Deloitte calls a week the leading practice for pre-read lead time in Tips for improving board communications and effectiveness. That cycle works for a quarterly agenda. A term sheet can change in a day.
Two Hours and an Agreement Nobody Read
Jerome Van Gorkom, board chair and chief executive of Trans Union, arrived at a $55 per share price with help from one other officer and raised it with a prospective buyer before involving his board. That's the account in the Delaware Supreme Court's opinion in Smith v. Van Gorkom. The buyer required a decision within 3 days. The board met on Saturday, September 20, 1980, for about 2 hours. Directors relied on a 20-minute oral presentation, and no director read the merger agreement before it was signed that evening.
On January 29, 1985, the court held that the board's approval was not the product of an informed business judgment. The majority found directors grossly negligent for approving a sale on 2 hours' consideration, without prior notice, and "without the exigency of a crisis or emergency." The directors were seasoned executives, and experience couldn't stand in for information. The court did not require a fairness opinion or outside valuation. It faulted the board for accepting an untested price and never considering a recess or an extension of the buyer's Sunday deadline.
Two justices dissented, and the ruling is a 1985 Delaware decision on a public company cash-out merger, so read it as a picture of the standard rather than a current checklist. The deadline came from the buyer. The failure sat in how the board received it.
Boards Watch Milestones While Value Moves Elsewhere
Deloitte surveyed 126 life sciences executives with cross-border deal experience involving Japanese and non-Japanese organizations, and interviewed 12 more, in Driving value in cross-border M&A deals. Most rated their boards effective, and the gap sat in where boards put their attention. They concentrated on signing, closing, and formal approvals, while value takes shape earlier through strategy, diligence, and operating model choices and gets realized or lost after the close. Deloitte argues boards should move from approving at set moments to engaging continuously. Read the survey with care. It covers one sector and comes from a firm that advises on M&A. It shows what experienced dealmakers perceive, not that any board design produces better outcomes.
David Fubini of Harvard Business School and Patrick Sanguineti reach a close conclusion from the board's side in Why Mergers Fail When Strategy Is 'Right', published in Directorship, the magazine of NACD. Its key points say that how two companies are combined after closing decides whether a merger creates or destroys value, and that boards should push management past the public deal story toward a precise operating rationale that every valuation and diligence decision rests on, and that is tested rigorously. Only the introduction and key points are open to nonmembers, so I rely on those.
Sabshon puts the post-close handoff bluntly, saying "After a transaction closes, it is the company that has to make the transaction successful." The same article adds that boards should require a post-deal plan with measurable targets before approving a transaction, then keep testing the deal's assumptions.
More Engagement Does Not Mean More Management
Involvement can overshoot. A board that follows every diligence workstream ends up managing the deal. A 2016 Deloitte paper, M&A: The intersection of due diligence and governance, draws the line plainly. The board oversees diligence and doesn't perform it, and the independence of public company boards is what makes that oversight useful. Directors also carry no completion bonuses or success fees, which can bias management and advisers.
The line moves with circumstances. NACD notes in its Director Essentials piece Board and Management Roles, citing its Future of the American Board report, that boards typically step closer to operations when a company faces a crisis or a major change in strategy or scale. A large acquisition can fit that pattern, though that reading is mine and not the report's. Deloitte's Board governance in 2026 adds that directors keep their compliance duties while taking a more forward-looking view of risk.
The practical answer is narrow involvement in the right places. A board can test the strategic thesis without rebuilding the model and set the limits inside which executives move quickly.
The Board's Role in M&A Is Built Before the Deal Arrives
PwC puts a pointed test to boards in 2026 corporate governance trends to watch. PwC tells boards to test their own readiness for a compressed timetable. Can directors get the right information in time, and does anyone at the table have the expertise to judge a complex transaction? If not, committee structures may need to change or outside advisers may need to join. PwC also urges boards to agree on deal criteria, including when to walk away, before a live transaction adds pressure.
NACD treats preparation as a task that spans the whole deal. Its The Oversight of M&A lays out the board's role across seven phases of the deal life cycle, and its The Phases of M&A: Questions Directors Can Ask starts with process questions. What process exists for the board and management to weigh M&A and its alternatives, and what criteria bring a transaction to the board? Jerry Martin and Vikas Sekhri of RSM US LLP write in The Governance Challenges of M&A in a Changing Market that governance structures must adapt during a transaction, and that a board may need new skills, committees, or directors, or even a new board. RSM US LLP is an advisory firm, so read that as an adviser's view.
Structure beats urgency. In its cross-border report, Deloitte points to clear delegation thresholds, set approval timelines, and empowered committees as ways to keep momentum while preserving control. Delegation carries its own risk, because a fast committee can leave the rest of the board thinly informed. Independence matters too.
Under the Takeover Code, a target board must obtain competent independent advice on an offer, and an adviser rewarded if the offer fails would normally be disqualified, according to Slaughter and May. The Trans Union board had no valuation study in front of it. A board that has already decided who tests management's numbers doesn't have to improvise that answer on a Saturday.
Questions to Settle Before the First Approach
None of these has a universal answer. Company size, ownership, jurisdiction, and deal type all change the right design.
Who can convene the full board on 24 hours' notice, and what must directors hold in writing before they vote?
Does a chartered standing committee exist, with stated authority, decision thresholds, and a duty to report to the full board? Which decisions can it make between meetings?
Have directors and management agreed on valuation limits, financing, and red-line terms before an offer arrives? Walk-away criteria belong on paper before a price is on the table.
Management's valuation needs an independent test. Who runs it, and how is that adviser paid?
During active negotiations, what will directors receive and how often? Short updates may serve better than a thick deck.
Does the annual board evaluation test deal readiness, and who owns the board's checkpoints after closing?
Your answers will differ on a private company board, a family business board, or a board with a private equity owner. The sources here lean toward the United States and the United Kingdom, and qualified counsel should confirm what applies to yours.
A board can't choose when the first approach arrives. It can choose whether directors meet that moment with a process they built or a deadline someone else wrote. The board's role in M&A now includes that choice, and it gets made long before the deal does. If a serious approach reached your board this week, what would directors hold in their hands before they voted?
This article offers general information about board governance. It isn't legal advice, and director duties and takeover rules differ by jurisdiction and company type. Consult qualified counsel about any specific transaction.
When a Transaction Puts Your Governance Under Pressure
Aspirations Consulting Group works with executives and other leaders at the points where growth, transition, or performance pressure meets a hard decision, including the moments when a transaction tests how an organization governs itself. See how the firm supports leaders at these inflection points.
Get Board-Level Thinking Every Weekday
ACG Strategic Insights publishes every weekday for more than 10 million executives and other leaders worldwide, and you can request a complimentary subscription to receive each edition.
Thanks for reading!
~ Jerry Justice
Living to Serve, Serving to Lead™


Comments