
The Q3 Close and the Four Numbers That Actually Predict Q4

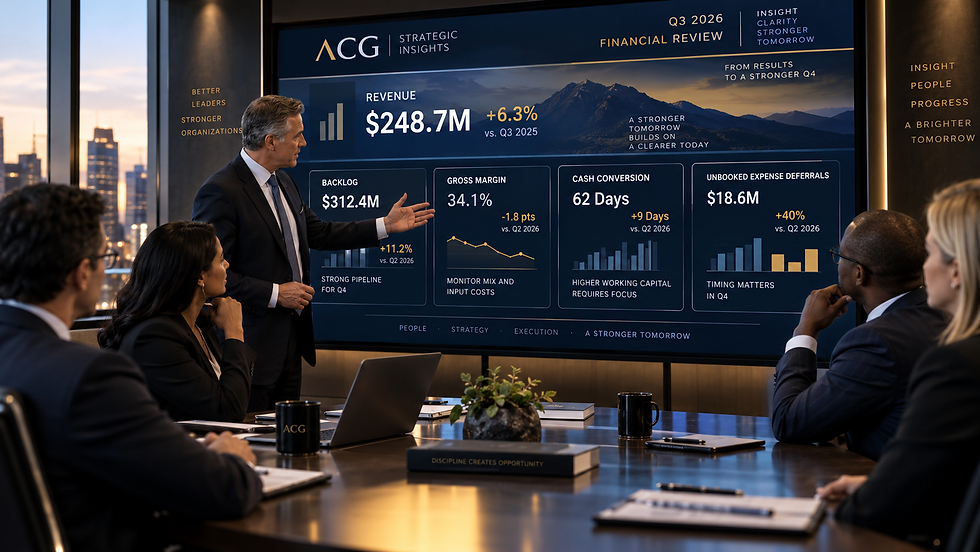
Quarter-end financial packages have a talent for making the past look tidy. Revenue is closed. Expenses are reconciled. Variances have explanations attached to them. By the time the Q3 package lands on your desk, 3 months of messy operating reality have been converted into orderly columns, and that tidiness can create a confidence about Q4 the numbers have not actually earned.
This is the third piece in a series that began with the Q1 close in March and continued with the Q2 close in June. The Q1 close asked whether the year's plan still held. The Q2 close asked whether the plan survived contact with the market. The Q3 close asks the sharpest question of the three, because there is only one quarter left to answer it.
A strong Q3 revenue number generates immediate optimism. It reassures boards and leadership that annual targets remain within reach. Yet in advisory engagements across middle-market enterprises, Aspirations Consulting Group consistently observes that top-line revenue, evaluated on its own, is the least useful figure in the entire close package for predicting what Q4 will actually deliver.
Why Revenue Alone Misleads You at the Q3 Close
Revenue tells you how much business crossed the accounting line during Q3. It does not tell you how much economic strength crossed into Q4.
A strong Q3 revenue number can sit on top of a weakening business. A soft one can sit on top of a business about to accelerate. Revenue measures past execution. It offers almost no insight into the operational stress, working capital strain, or margin erosion incurred to deliver that result, and executive teams who anchor Q4 planning on the Q3 revenue figure alone end up planning for a quarter that already happened, dressed up as a forecast.
Four numbers correct for that. Each one carries forward-looking information that revenue, by its nature as a trailing metric, cannot provide.
Backlog Coverage and Conversion Velocity Show You How Much of Q4 Is Already Won
Start with backlog, or booked and committed business relative to your Q4 target. Divide what is already under contract, in a signed order, or in a confirmed project schedule by the revenue target for the fourth quarter.
Raw backlog size can deceive on its own. The number worth interrogating is how much of that backlog consists of firm, near-term delivery dates versus delayed or contingent commitments. If conversion velocity slowed during Q3, meaning projects took longer to move from signed contract to billable milestone, Q4 revenue recognition will stall regardless of how large the backlog looks on paper.
Set a coverage threshold with your finance leader before the number arrives, not after. A pre-agreed line, whether that is 50%, 60%, or a figure specific to your sales cycle, keeps the leadership team focused on what to do next rather than on relitigating what the number should have been. Below the line, the next 90 days belong to pipeline and closing activity. Above it, they belong to delivery, capacity, and protecting the margin on business already won.
The Margin Trend Your Close Package Buries in a Single Line
Most close packages show gross margin as one number for the quarter. That single figure hides the trend inside it, and the trend carries most of the forecasting value.
Compare margin by month, not just the quarterly average, and break it down by customer segment, product or service line, and geography where the business operates. A margin that opened Q3 strong and eroded by September is telling you something the quarterly average alone will not show. Premium freight charges, overtime labor, price discounts, and supply chain expediting costs frequently hide inside a strong revenue quarter, quietly accelerating the cost to deliver it faster than the top line itself grew.
Margin often reveals the trade-off a business has been avoiding. Revenue acquired at increasingly poor economics can satisfy a quarterly target while quietly weakening the business that has to deliver the next one. A rising margin trend across the quarter suggests operational discipline likely to continue into Q4. A falling trend, even with a respectable quarterly average, calls for direct engagement from the operating leaders closest to cost and pricing before Q4 begins, not after it ends.
Cash Conversion Timing Reveals the Liquidity Behind Q4
Recognizing revenue on an accrual basis in Q3 offers no guarantee that cash will be there to fund Q4 operations. J.P. Morgan defines days sales outstanding as the number of days it takes to collect cash from customers, one of three components, alongside days inventory outstanding and days payable outstanding, that make up the cash conversion cycle, as detailed in its How to Benchmark Your Working Capital guide.
If Q3 revenue climbed largely because of late-quarter sales pushed through on extended terms or concessions, the organization enters Q4 carrying a hidden liquidity constraint. Watch the aging schedule as closely as the headline figure. A spike in receivables aged past 60 days can sit underneath a stable overall DSO number, and that concentration is often the earliest visible sign of financial stress in a customer base, arriving well before it shows up as a cancelled order or a lost renewal.
Revenue is vanity, profit is sanity, and cash is reality, as the old business saying goes. The Q3 close is where that reality either confirms the quarter or quietly contradicts it. If cash collections stall in October and November, the organization can struggle to cover Q4 payroll, vendor obligations, and seasonal inventory needs without leaning on credit it would rather not use.
Unbooked Expense Deferrals Are the Liabilities Q4 Inherits
To hit a Q3 earnings or cash flow target, operating units frequently defer expenses that do not disappear, they migrate. Maintenance gets rescheduled. Open headcount goes unfilled. Marketing spend is frozen. Inventory replenishment is delayed.
The Q3 close package carries clear evidence of this when operating expenses drop below baseline run rates while revenue stays high. Those deferred costs arrive in Q4 as mandatory obligations rather than discretionary choices. When inventory gets depleted to fulfill September shipments, Q4 has to absorb the cash outflow to restock, and a maintenance schedule pushed from August does not vanish, it simply waits for a more expensive moment to reappear.
Identifying these deferrals during the Q3 close lets finance leaders adjust the Q4 expenditure forecast before a budget shortfall becomes a surprise the leadership team runs into in November.
Reading the Four Numbers Together Before the Q4 Planning Meeting
None of these four numbers works in isolation. What should concern executives most is convergence. A quarter can close with record revenue while margin has declined for 3 consecutive months, backlog conversion has slowed, receivables are aging, and deferred expenses are stacking up behind it. That company did not necessarily have a bad Q3, but it is entering Q4 carrying four signals that deserve more weight than the revenue celebration.
The opposite pattern matters just as much. Revenue can finish modestly below target while margin improves, backlog converts faster, collections accelerate, and no material expense deferrals sit hidden in the numbers. That organization may enter Q4 with more financial capacity than its headline result suggests.
Before the Q4 planning meeting, put these four questions in front of the leadership team:
How much of the Q4 target is already under contract, and how fast is that backlog actually converting to billable revenue?
Has gross margin held steady month over month, or has it eroded beneath a quarterly average that looks fine on the surface?
Are Q3 receivables collecting on standard terms, or is a concentration of aged accounts creating a liquidity gap heading into October?
What expenses or inventory replenishment did Q3 defer that Q4 must now absorb?
A forecast that ignores what these four numbers reveal is not really a forecast. It is an old plan with a new date.
Fiscal calendars vary by jurisdiction and industry, and leadership teams operating outside a standard calendar year should apply this framework to whatever quarter sits 3 months ahead of their own year-end close.
Turning Your Close Package Into a Forecasting Tool
Aspirations Consulting Group works directly with finance and executive leadership teams to build the reporting discipline behind these four numbers, converting a routine quarterly close into a genuine forecasting tool. Learn more about ACG's financial strategy advisory work at aspirations-group.com.
Start Q4 With the Full Picture
Executives who want this kind of analysis every day can request a complimentary subscription to ACG Strategic Insights.
Thanks for reading!
~ Jerry Justice
Living to Serve, Serving to Lead™

Comments