
What Shareholder Activists and Strategic Acquirers Have in Common

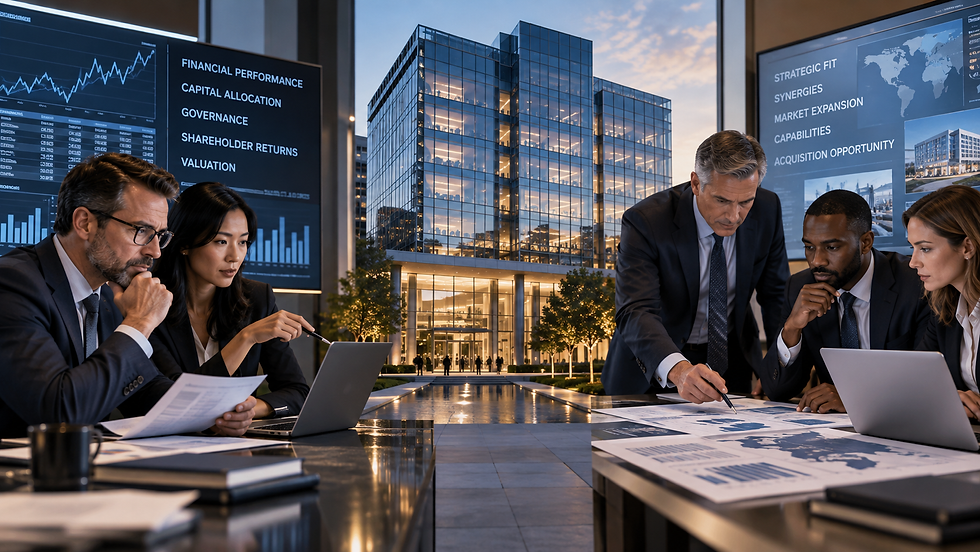
Boards spend enormous energy preparing for one of these two outside parties and almost none preparing for the other. That split in attention makes little sense once you look at what actually draws each of them to a company's door. Shareholder activists and strategic acquirers arrive through different front doors, but they are working from the same set of clues.
The activist buys a stake and argues the company is worth more than its current strategy is producing. The acquirer considers buying the company because it believes the assets are worth more under different ownership. One wants influence, the other wants control, and their methods and time horizons differ. Yet before either one acts, both study remarkably similar evidence.
Shareholder Activists and Strategic Acquirers Read the Same Signals
A shareholder activist studies a public filing looking for a gap between what a company is worth and what the market currently pays for it. A strategic acquirer studies the same filing looking for the same gap. The starting point is identical.
Underneath the financial analysis sits a simpler question: who is the best owner of these assets? Management naturally answers from inside the organization, because history put the businesses there. An outsider has no such obligation. A strategic acquirer may see a division that fits better with its own distribution network. An activist may see the same division and conclude shareholders would benefit if it were sold. Different destination. Same underlying question.
A director who understands what draws activist attention already understands most of what draws acquirer attention, and the reverse holds too. Once boards see the overlap, activism defense and acquisition readiness stop looking like separate disciplines.
Undervalued Assets Draw Both Kinds of Attention
Real estate carried at historical cost while sitting on land worth several multiples of that figure. A patent portfolio generating royalty income far below what a licensing specialist could extract from it. A subsidiary worth more sold to a strategic buyer than kept inside a diversified parent. Every one of these gaps shows up the same way to an outsider running a sum-of-the-parts model.
An activist sees the gap and writes a letter demanding a sale or a new capital allocation policy. An acquirer sees the same gap and picks up the phone. The board that has already closed the gap, by monetizing the asset or explaining the logic for holding it, has removed the opening for both.
Markets outside North America present this pattern just as often. European conglomerates with underappreciated divisions and Asian family-controlled groups sitting on legacy property holdings face the identical calculation. The geography changes. The arithmetic does not.
An Underleveraged Balance Sheet Sends the Same Signal Twice
A company holding cash and unused borrowing capacity well beyond what its operations require reads as conservative to its own management team. To everyone else, it reads as an opportunity. An activist reads a light balance sheet as room for a buyback, a special dividend, or a debt-financed recapitalization. An acquirer reads the identical balance sheet as a target that can help finance its own purchase, since the buyer inherits that unused capacity the moment the deal closes.
This is not a new observation. McKinsey & Company research on takeover vulnerability found that extraordinary cash balances, high working capital, and underleveraged balance sheets all attract outside attention, for reasons both good and not so good. Separately, McKinsey consultant Sandra Oberhollenzer has described four levers activists typically pull, including mergers and acquisitions, and notes that activists often push companies to sell assets they view as noncore or lower margin, as detailed in McKinsey's The Pros and Cons of Activist Investors.
Boards often defend a conservative capital structure as prudent risk management, and sometimes that defense holds. But prudence and inertia can look identical from the outside, and both activists and acquirers are skilled at telling the difference. Capital allocation communicates what leadership believes about the company's opportunities, and when the balance sheet and the stated strategy tell different stories, outsiders notice. A board that reviews its capital structure against a stated purpose, as Preempting Hostile Takeovers recommends, denies both parties the easiest argument they have.
Strategic Drift Is the Clearest Invitation of All
Undervalued assets and light balance sheets are financial signals. Strategic drift is a narrative signal, and it may be the strongest one of the three. A company that has drifted from a clear strategy into a collection of businesses held together by history rather than logic sends a message to anyone paying attention: management cannot articulate why these pieces belong together, and the market applies a discount for that uncertainty.
Strategic drift rarely announces itself in a single decision. It accumulates over several years, through an acquisition made to enter an adjacent category, a legacy division kept alive out of loyalty, and a core business quietly starved of reinvestment. Each choice made sense on its own. Together, they leave a portfolio no one on the board could defend in a single sentence if a skeptical outsider asked them to try.
An activist steps into that vacuum with a thesis built around breaking the company apart. A strategic acquirer steps into the same vacuum with a thesis built around removing one piece and folding it into a business where it fits better. What one calls noncore, the other calls a strategic fit waiting to happen. In a 2015 presentation on acquisition-driven growth, investor Bill Ackman argued that in the businesses he called platform companies, "capital allocation and acquisitions are a core competency," and a significant focus of senior management and the board alike, as reported in Activist Insight's Activist Investing: An Annual Review of Trends in Shareholder Activism 2016. That same discipline is exactly what a board should expect an outsider to apply when evaluating its own portfolio.
The market does not usually penalize a company for lacking opportunity. It penalizes the board for failing to make clear choices about the assets it already owns.
Why the Distinction Still Matters for Your Board
None of this argues that activist defense and acquisition readiness are the same exercise. They are not.
Dimension | Shareholder Activist | Strategic Acquirer |
Primary Goal | Short- to medium-term equity appreciation and capital return | Long-term operational combination and capability expansion |
Approach | Public campaign, proxy engagement, board seat requests | Private negotiation or a formal M&A process |
Capital Required | A minority stake amplified through voting power | Full purchase price or a controlling interest |
Effect on Governance | External pressure forcing internal change | A complete transfer of governance authority |
An activist campaign plays out in public, through proxy contests and open letters, running through investor relations and a public narrative. An acquirer's approach plays out in private, through a confidential call to the chief executive officer or the board chair, running through a different set of advisors and a different calendar. The mechanisms diverge. The underlying vulnerability does not.
This pattern holds well beyond any single market. A mid-cap manufacturer in Germany facing pressure from a European activist fund is being read by the same valuation logic that would draw an acquirer based in Japan or the United States. The playbook reflects local disclosure rules and shareholder rights regimes, so boards should seek jurisdiction-specific counsel. But the underlying signal, a gap between stated value and demonstrated performance, reads the same in every market.
Activity data bears this out. Lazard's Review of Shareholder Activism – H1 2026 tracked 184 new activist campaigns globally in the first half of the year, the busiest six-month period on record. M&A objectives appeared in 40% of those campaigns, capital allocation demands in 39%, and strategy demands in 23%, the exact intersection this article is describing. An underperforming business unit is a strategy question. Excess cash is a financial question. A company that repeatedly postpones those decisions eventually has a governance question, and sometimes an outsider turns all three into an M&A question.
Building a Board That Sees Both Coming
This is where the overlap between shareholder activists and strategic acquirers becomes genuinely useful. Commission an honest sum-of-the-parts valuation on a regular cycle, not only when a crisis forces the question. Review the balance sheet against a stated capital allocation policy rather than historical habit. Require every business unit to justify its place in the portfolio in terms a skeptical outsider would accept.
A practical way to run this exercise is to apply two outside lenses during a board session. First, ask what an activist would argue if it acquired a meaningful position tomorrow. Then change the lens and ask what a logical acquirer would value differently. The overlap between those two answers deserves the board's particular attention. Three questions can anchor that session:
The asset discipline test. Has every business unit and asset class been evaluated over the past four quarters to determine whether it generates a higher return under current ownership than it would if divested or spun off?
The capital allocation test. Does the balance sheet posture actively serve the company's long-term growth strategy, or has the company been accumulating reserves simply to avoid a difficult investment decision?
The strategic clarity test. Can the independent directors articulate the company's core advantage in two sentences, without leaning on generic growth language or unproven adjacencies?
Boards that do this work learn something useful along the way. The same analysis that closes the door on an activist campaign also closes the door on an unsolicited approach from a strategic buyer, or positions the board to negotiate from strength rather than react from surprise when a sale genuinely serves shareholders. It also means outside advisors move faster, since a client with the valuation math already assembled moves faster than one building that case under pressure.
Preparation does not force a choice between defending independence and staying open to a transaction. It puts the board in control of which engagement happens, and on what terms, rather than leaving that choice to whoever notices the gap first.
Legal disclaimer: This article is provided for general informational purposes and does not constitute legal, financial, or investment advice. Boards and executives should consult qualified advisors before acting on matters of shareholder activism, mergers and acquisitions, or capital structure.
A Working Session for Your Next Board Meeting
Aspirations Consulting Group helps boards run the readiness work described above, from sum-of-the-parts valuation reviews to capital allocation policy to advisory support on either side of a transaction. Explore ACG's governance and M&A advisory services to see how it applies to your company.
Spot the Next Signal Before It Reaches Your Boardroom
For more insights like this delivered daily, sign up for a complimentary subscription to ACG Strategic Insights.
Thanks for reading!
~ Jerry Justice
Living to Serve, Serving to Lead™
Comments